Centennial Condo Association Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
Condo association boards in Centennial face a unique insurance puzzle. You're not insuring a single-family home or a commercial office park. You're protecting a shared community, its
physical structures, its finances, and the volunteers who govern it. Colorado's insurance market has shifted dramatically in recent years, with the state now ranking as the
6th most expensive for homeowners insurance, where average annual premiums hit $4,164, a 100% increase from just a few years ago. That spike doesn't just affect individual
unit owners. It ripples directly into what condo associations pay for master policies, liability protection, and specialized coverages. If your board hasn't reviewed its insurance program recently, you're probably carrying gaps you don't know about, or paying for overlaps you don't need. This guide breaks down the six core coverage areas that every Centennial condo association should understand: buildings, liability, D&O, crime, equipment breakdown, and deductibles.
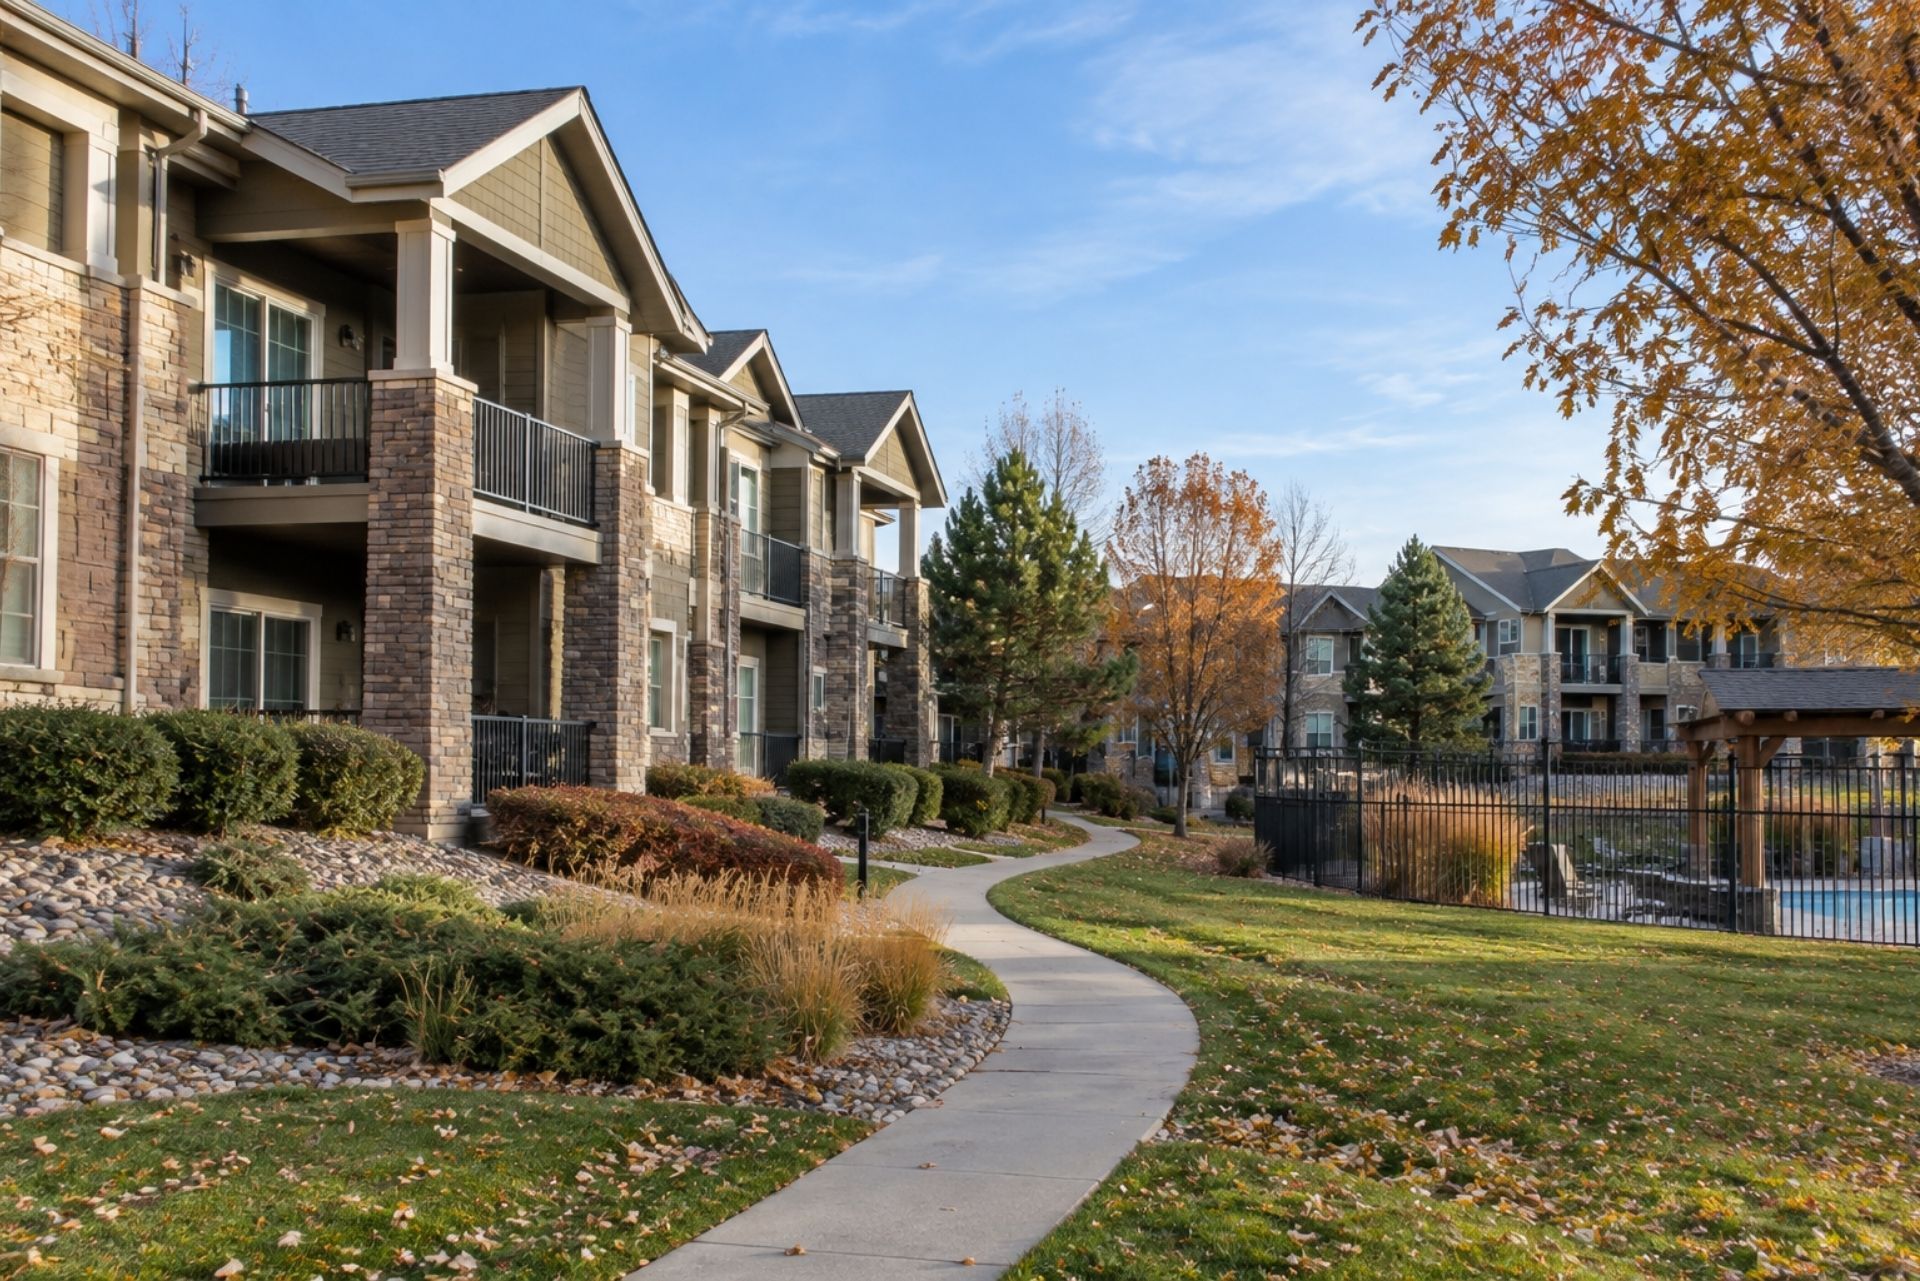
Understanding Master Policy Basics in Centennial
The master policy is the backbone of your association's insurance program. It covers the physical structures and common elements that belong to the association rather than individual unit owners. Think of it as the policy that protects everything from the exterior walls and roof down to shared hallways, lobbies, pools, and parking structures.
Colorado law and your association's governing documents dictate what the master policy must cover. Most lenders, including Fannie Mae, now require associations to carry specific coverage types and limits. Recent changes to project standards and property insurance requirements mean that boards ignoring these updates risk making their units harder to finance, which directly hurts property values across the community.
Your master policy should be reviewed annually, ideally 90 days before renewal. Replacement cost estimates need updating because construction costs in the Denver metro area, including Centennial, have climbed sharply since 2023.
Building and Property Coverage Limits
Setting the right coverage limit is one of the most consequential decisions your board will make. The limit should reflect full replacement cost of all insured structures, not market value or the original construction price. These are different numbers, and confusing them is a mistake we see constantly.
Get a professional replacement cost appraisal every three to five years. Between appraisals, apply an inflation factor. If your 200-unit complex was appraised at $40 million in 2023, that number could easily be $46 million or more in 2026. Underinsuring by even 10% can trigger coinsurance penalties, meaning the carrier pays only a proportional share of a loss. On a $2 million fire claim, that penalty could cost your association hundreds of thousands of dollars.
Bare Walls vs. All-In Coverage Models
This distinction trips up more boards than almost anything else. A bare walls policy covers the building structure as originally built, stopping at the interior surface of exterior walls, the unfinished side of ceilings, and the subfloor. Unit owners are responsible for insuring everything inside: cabinets, flooring, fixtures, appliances, and improvements.
An
all-in policy (sometimes called "single entity" or "all-inclusive") covers the unit interiors as originally built, including standard fixtures and finishes. Your CC&Rs should specify which model applies. If the documents are ambiguous, get a
legal opinion. The wrong assumption here creates a coverage gap that surfaces only after a loss, and by then it's too late. We've seen disputes between associations and unit owners drag on for months because nobody clarified this before the pipe burst.
By: John Jacquat
Founder & President
Protecting the Association from Liability and Financial Loss
Physical property coverage gets most of the attention, but liability and financial protection are equally critical. A slip-and-fall lawsuit, a board decision gone wrong, or an embezzlement scheme can threaten your association's reserves just as fast as a hailstorm.
Centennial associations should think of liability and financial coverages as a three-legged stool: general liability, D&O, and crime/fidelity. Remove one leg and the whole thing collapses. Colorado's HOA governance requirements place specific duties on boards, and failing to carry adequate insurance can itself become a breach of fiduciary duty.
General Liability for Common Areas
General liability insurance covers bodily injury and property damage claims arising from the association's common areas and operations. A visitor slips on an icy sidewalk outside the clubhouse. A child is injured at the pool. A tree on association property falls onto a neighbor's car. These are all general liability claims.
Most associations carry $1 million per occurrence with a $2 million aggregate. Larger communities or those with amenities like pools, fitness centers, or playgrounds should consider higher limits or an umbrella policy that adds another $1 million to $5 million on top. The cost of an umbrella is typically modest relative to the protection it provides. Don't skip it to save $800 a year.
Directors and Officers (D&O) Protection
Board members are volunteers, but they make decisions that carry real legal weight. D&O insurance protects individual directors and the association itself against claims alleging wrongful acts in the management of the community. Think failure to enforce rules consistently, mismanagement of funds, or discrimination in rule enforcement.
Colorado has seen a rise in HOA-related litigation, particularly around new laws governing board transparency and owner rights. D&O policies typically cover defense costs even if the claim is groundless, which matters because legal fees alone can run $50,000 to $150,000 before a case ever reaches trial. Without D&O coverage, good luck recruiting volunteers to serve on your board.
Crime and Fidelity Insurance Requirements
Crime and fidelity coverage protects against theft or dishonest acts by board members, property managers, employees, or volunteers who handle association funds. Fannie Mae requires this coverage for associations seeking loan eligibility, and most governing documents mandate it as well.
The coverage limit should equal at least the maximum amount of funds the association holds at any point during the year, including reserves. For a Centennial association with $500,000 in reserves and $200,000 in operating funds, a $700,000 fidelity bond is the minimum. Some carriers offer broader crime policies that also cover computer fraud, forgery, and social engineering scams, all of which have become more common as associations move to digital payment platforms.
Specialized Risks: Equipment Breakdown and Deductibles
Standard property policies often exclude mechanical and electrical breakdown. That's a problem for associations with boilers, elevators, HVAC systems, and other shared mechanical equipment. Deductibles, meanwhile, are the portion of every claim the association pays out of pocket, and they've been climbing fast in Colorado.
HVAC and Mechanical Systems Coverage
Equipment breakdown coverage (sometimes called boiler and machinery insurance) fills a specific gap in your property policy. If the central boiler fails due to an electrical surge, a standard property policy won't pay for it because there's no "covered peril" like fire or wind involved. Equipment breakdown coverage steps in for mechanical failure, electrical arcing, motor burnout, and similar events.
For associations with central heating/cooling plants, shared water heaters, or elevators, this coverage is essential. A single commercial boiler replacement can run $80,000 to $150,000. Many equipment breakdown policies also cover the cost of temporary heating or cooling while repairs are made, which keeps residents from filing complaints or withholding assessments.
Managing High Deductibles and Loss Assessment
Colorado's insurance market has pushed deductibles higher across the board. It's not unusual for Centennial condo associations to carry $10,000, $25,000, or even $50,000 deductibles on property claims, especially for wind and hail. Some policies now feature percentage-based deductibles tied to the total insured value, meaning a 2% deductible on a $40 million building equals $800,000 out of pocket.
Your association needs a clear deductible responsibility policy. Who pays the deductible when a claim originates from a single unit? Most well-run associations assign the deductible to the unit owner whose unit caused or was the origin point of the loss. This policy should be adopted formally and communicated to all owners. Individual unit owners can purchase
loss assessment coverage through their HO-6 policies to help cover their share.
Comparison of Core Coverage Features
| Coverage Type | What It Protects | Typical Limits | Who Needs It |
|---|---|---|---|
| Building/Property | Physical structures, common elements | Full replacement cost | All associations |
| General Liability | Bodily injury, property damage in common areas | $1M per occurrence / $2M aggregate | All associations |
| D&O | Board decisions, governance claims | $1M - $5M | All associations with a board |
| Crime/Fidelity | Theft by insiders, fraud | Equal to max funds held | Required by Fannie Mae and most CC&Rs |
| Equipment Breakdown | Mechanical/electrical failure | Varies by equipment value | Associations with shared HVAC, elevators, boilers |
| Umbrella/Excess | Additional liability above primary limits | $1M - $10M | Communities with pools, gyms, or high foot traffic |
Common Questions About Centennial Condo Insurance
Does the master policy cover my personal belongings inside my unit? No. The master policy covers the building structure and common areas. Your personal property, upgrades, and interior finishes (depending on whether the policy is bare walls or all-in) require your own HO-6 condo unit owner policy.
How often should our board review the master policy? At minimum, annually, ideally 90 days before renewal. Any time the association completes a major renovation, adds amenities, or sees significant changes in reserve balances, the policy should be updated.
Are board members personally liable if the association doesn't carry enough insurance? Potentially, yes. Colorado law holds board members to a fiduciary standard. Failing to maintain adequate insurance could be considered a breach of that duty. D&O coverage helps protect against such claims, but it doesn't excuse the board from carrying proper coverage in the first place.
What happens if our association can't afford the deductible on a large claim? The association may need to levy a special assessment against all owners. This is why maintaining healthy reserves and having a clear deductible responsibility policy in your governing documents matters so much.
Can we reduce premiums by raising our deductible? Yes, but proceed carefully. A higher deductible lowers your annual premium, but it increases your out-of-pocket exposure on every claim. Make sure your reserves can absorb the higher deductible before making that trade-off.
Is equipment breakdown coverage required? Not by law, but if your community has shared mechanical systems, going without it is a gamble. One boiler failure or elevator malfunction could wipe out your reserve fund.
Making the Right Choice for Your Community
Getting condo association insurance right in Centennial isn't a one-time task. It's an ongoing responsibility that requires your board to stay current with Colorado's shifting insurance market, evolving lender requirements, and your community's own changing risk profile. The six coverage areas we've covered, buildings, liability, D&O, crime, equipment breakdown, and deductibles, form a complete protection framework when properly structured.
Start by pulling your current policy and comparing it against the categories in the table above. Identify gaps. Get a replacement cost appraisal if yours is more than three years old. Talk to a broker who specializes in community association insurance rather than a generalist who writes mostly auto and homeowners policies.
Your board's job is to protect the community's physical assets and financial health. The right insurance program is how you do that without putting volunteers, reserves, or property values at risk. Don't wait for a claim to find out what you're missing.
ABOUT THE AUTHOR:
John Jacquat
As President of Pure Risk Advisors, I’m dedicated to helping clients protect what matters most through clear, personalized insurance solutions. Since 2009, my focus has been delivering trusted coverage and guidance for individuals and businesses across Colorado and beyond.
The Pure Risk Process
Process of Working With A Business Insurance Agent in Colorado
Risk Analysis & Tailoring
Embark on a meticulous exploration of your business's unique vulnerabilities and aspirations. Pure Risk Advisors goes beyond mere coverage, ensuring you're equipped with solutions finely tuned to Colorado’s distinct business landscape.
Strategic Business Consultation
Dive deep into a strategic session with our seasoned specialists. By delving into your business model, aspirations, and challenges, we align our insurance recommendations not just to protect but to propel your business forward, keeping in mind Colorado’s intricate regulatory environment.
Swift Policy Integration
Upon discerning the optimal protection strategy, we streamline the activation process. Partnering with Pure Risk Advisors means more than just business insurance – it's about securing your enterprise's future with unmatched diligence and expertise in Colorado.
Pure Risk Advisors Team
Meet Our Colorado Professional Team Members
Meet the heart and soul of Pure Risk Advisors: our exceptional team. Each individual has been meticulously selected not just for their deep-rooted industry knowledge, but for their passion and commitment to genuinely serve our clients.
We pride ourselves on forging more than just business transactions; we build relationships. Our team doesn't see you as just another policy number. Instead, they view every interaction as a partnership, crafting solutions that resonate with your unique needs.
Dive in, get to know us, and discover firsthand why our team makes all the difference.
Client Testimonials
Amazing Feedback About Pure Risk Advisors

In today’s insurance marketplace, innovation and originality are important - but unless they’re accompanied by integrity and personalized service, they do little to accomplish a club owner’s goals. ACE National is proud to recognize John Jacquat and his company, Pure Risk Solutions, as one of our top-ranked premier industry providers. John has consistently mastered achievement in leadership, creating the best product for a client’s needs and following through on his word. I can recommend Mr. Jacquat without reserve if you’re in the market for club insurance.
Angelina Spencer
Executive Director of Ace National
Business Insurance Coverage in Colorado
Commercial Insurance Options
Business Owner's Policy
Coverage for property damage, liability, and business interruption combined.
General Liability Insurance
Protects against business liabilities like bodily injury and property damage.
Workers' Comp. Insurance
Covers employee injury costs, ensuring business and worker protection.
Professional Liability Insurance
Guard against professional mistakes, negligence, or services rendered failures.
Commercial Property Insurance
Broad protection against business-related injuries or property damage claims.
Commercial Auto Insurance
Coverage for business vehicles against damage, injury, or liability.
We've been serving Colorado Business Since 2009
Industries Served
Latest News & Blog
Read Our Latest Articles