Vail High-Value Condo and HOA Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
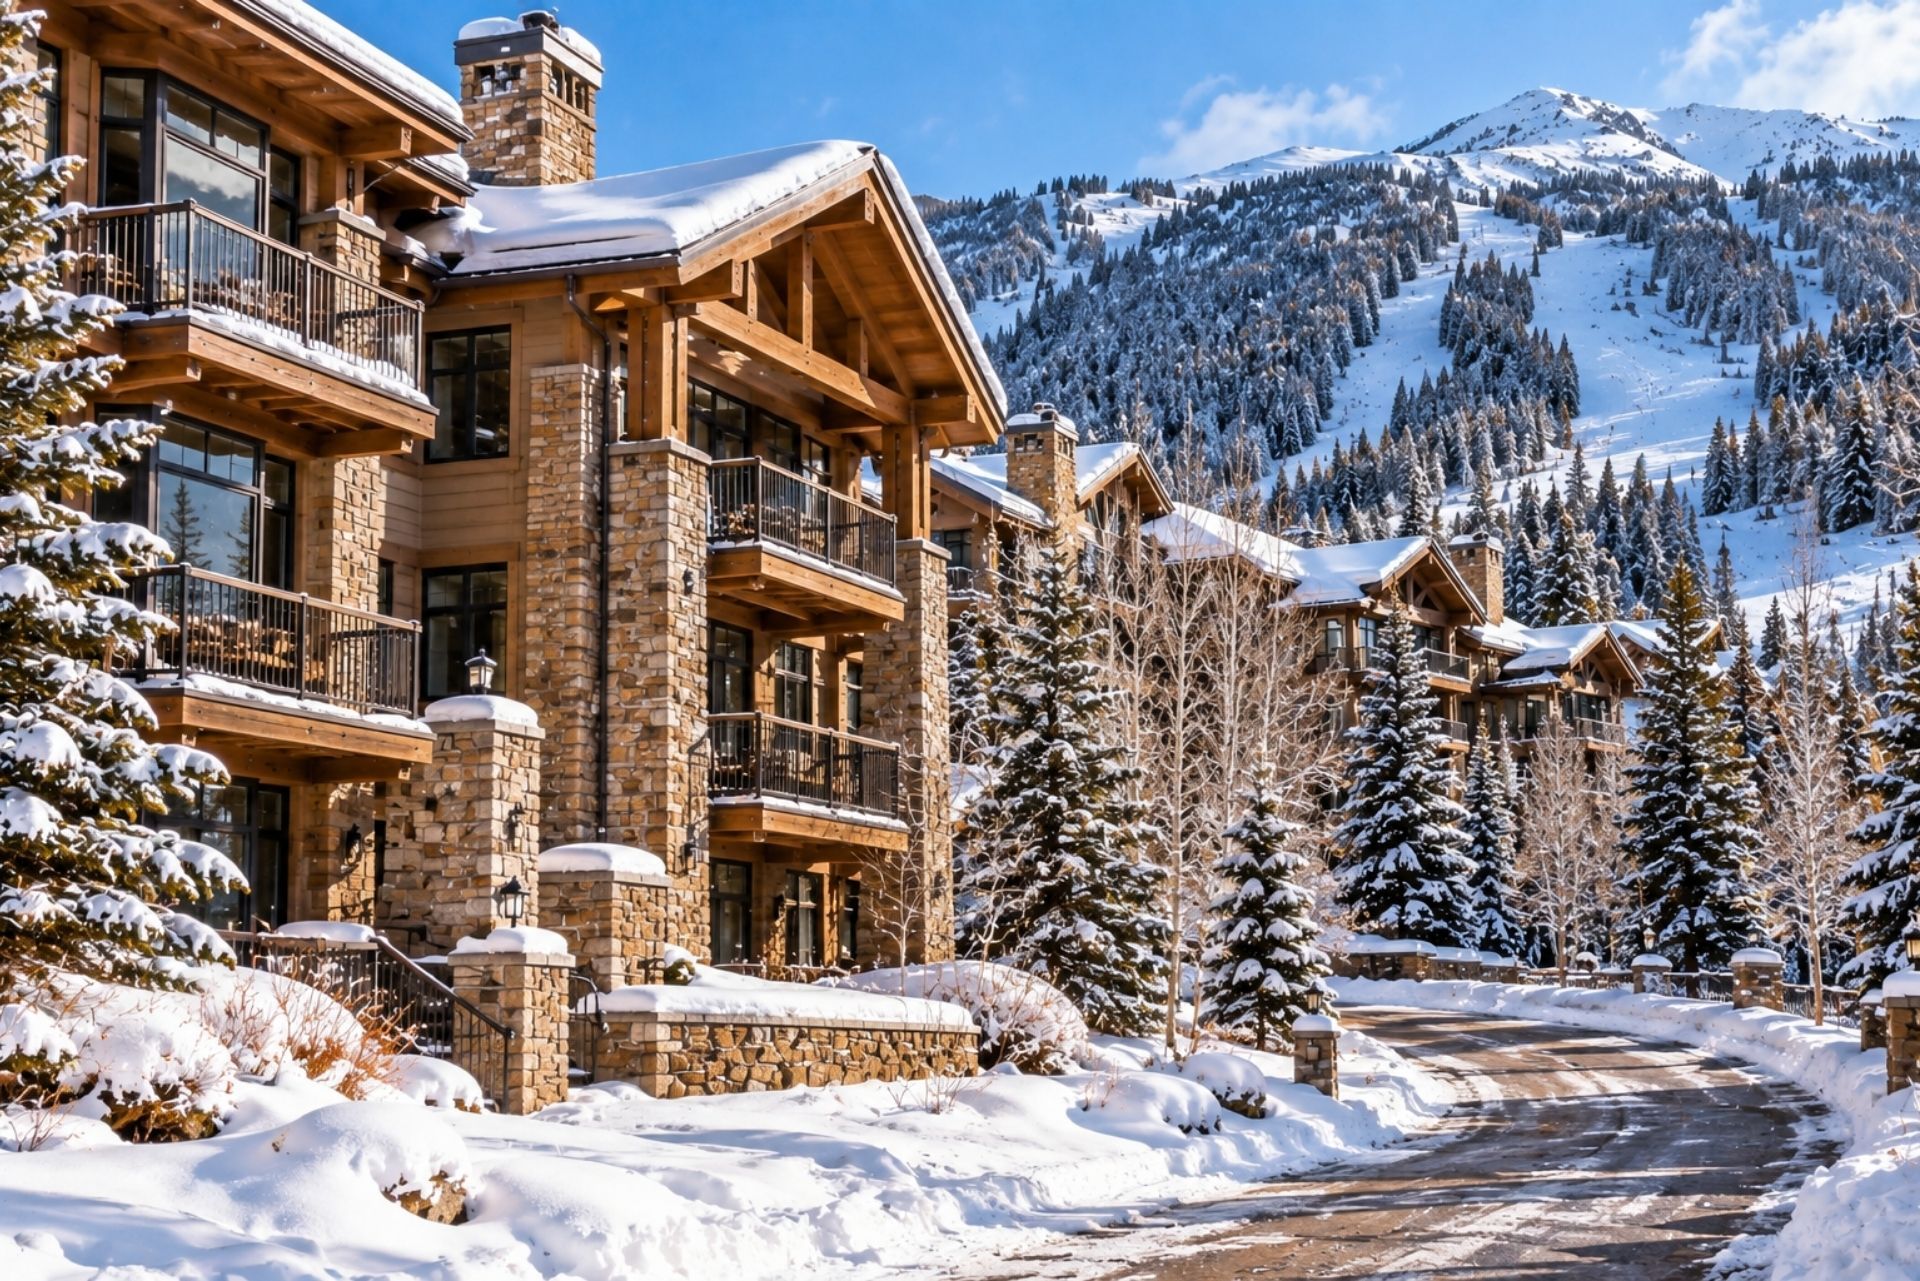
Vail's luxury condo market sits at the intersection of extraordinary property values and punishing alpine conditions. A single building here can carry $30 million or more in replacement value, and a single season can deliver wildfire smoke, a 300-pound-per-square-foot snow load, and burst pipes from a January cold snap. For board members and unit owners, getting insurance right isn't optional: it's the difference between financial security and a catastrophic special assessment. Colorado's condo association insurance environment has shifted dramatically in 2026, with premiums that have
roughly doubled since 2020, new lending rules from Fannie Mae, and fresh state legislation reshaping how associations operate. If you serve on a board or own a unit in a Vail high-value building, the stakes around wildfire, snow load, water damage, liability, and D&O coverage have never been higher. This guide breaks down what you actually need to know, section by section, so you can protect your mountain investment without overpaying or leaving gaps.
Understanding Vail's Unique Luxury Property Risks
Vail sits at roughly 8,150 feet, surrounded by national forest land and subject to weather patterns that would stress any structure. The combination of extreme cold, heavy snowfall, wildfire-prone forests, and ultra-high property values creates an insurance profile unlike almost any other market in the country. Board members who treat their Vail condo policy like a suburban Denver policy are making a costly mistake.
Environmental Hazards in High-Altitude Alpine Environments
Wildfire risk in the Vail Valley has intensified over the past decade. Even properties inside town limits face ember exposure from surrounding forest land. Insurers now routinely factor wildfire scores into premium calculations, and some carriers have pulled out of high-risk mountain corridors entirely.
Snow load is a less dramatic but equally expensive hazard. Flat or low-slope roofs on older Vail buildings can accumulate dangerous weight during multi-day storm cycles. Ice dams form at eaves and push meltwater under roofing materials, leading to interior water damage that's often misattributed to plumbing failures. These claims add up fast across a multi-unit building.
Water damage from frozen and burst pipes remains the single most common claim type for mountain condos. When a unit sits vacant midweek or between rental bookings, a thermostat failure can turn a luxury unit into a demolition project overnight.
The Impact of High Replacement Costs in Eagle County
Rebuilding a luxury condo in Eagle County costs far more per square foot than the Front Range average. Custom stone, timber framing, high-end mechanical systems, and limited contractor availability all drive costs up. If your master policy's replacement value hasn't been updated in two or three years, you're likely underinsured.
Appraisal gaps are a frequent problem we see with Vail associations. A board might carry $20 million in
building coverage on a property that would cost $28 million to rebuild at 2026 material and labor prices. That gap doesn't just affect the association: it affects every unit owner's equity.
By: John Jacquat
Founder & President
The Master Policy vs. Individual Unit Owner Coverage
Understanding how the master policy interacts with your personal HO-6 policy is one of the most misunderstood areas in condo insurance. The master policy covers the building's structure and common elements. Your HO-6 covers your personal property, interior improvements, and your share of any deductible the association passes through. Where the line falls between "building" and "unit" depends entirely on the type of master policy your association carries.
Bare Walls vs. All-In Coverage Models
Under a bare walls policy, the association insures the building's structural shell: exterior walls, roof, floors, common hallways, and shared mechanical systems. Everything inside the unit's drywall, including cabinets, flooring, fixtures, and appliances, is the owner's responsibility.
An all-in policy extends association coverage to original interior finishes and fixtures within each unit. If you've upgraded your kitchen with custom cabinetry, though, your HO-6 still needs to cover the difference between original spec and your improvements. Most high-value Vail condos carry all-in policies, but you should verify this with your board rather than assume.
Loss Assessment Coverage for Shared Amenities
When the association's master policy deductible kicks in after a major loss, that cost gets divided among unit owners through a special assessment. Standard HO-6 policies include $1,000 in loss assessment coverage, which is laughable for a Vail building where a single deductible can run $100,000 or more.
You should carry at least $50,000 to $100,000 in loss assessment coverage on your personal policy. This is one of the cheapest endorsements you can add, and it's the one most owners skip. After a large water damage or wildfire event, the special assessment alone can exceed the value of some owners' annual rental income.
Comparison: Standard vs. High-Value Condo Insurance
The table below highlights key differences between a standard condo association policy and one structured for high-value mountain properties like those in Vail.
| Coverage Feature | Standard Condo Policy | High-Value Vail Policy |
|---|---|---|
| Building Valuation | Actual cash value or basic replacement | Guaranteed/extended replacement cost |
| Deductible Range | $5,000 - $25,000 | $50,000 - $250,000+ |
| Wildfire Coverage | Included (limited markets) | Often requires surplus lines carrier |
| Snow/Ice Dam Damage | May exclude or sublimit | Full coverage with proper endorsement |
| Water Damage (Pipes) | Standard sublimits | Higher sublimits, equipment breakdown |
| D&O Liability | Often absent | Separate policy recommended |
| Loss of Rents | Basic coverage | Extended coverage for rental income |
| Ordinance or Law | Building value coverage | Recommended for older buildings |
One critical issue in 2026: Fannie Mae's LL-2026-03 rule now
caps master-policy deductibles at $50,000 for condo loans. Many Colorado associations carry deductibles well above $250,000 to keep premiums manageable. This creates a direct conflict: lower the deductible and premiums spike, or keep the high deductible and watch unit sales stall because buyers can't get conventional financing.
Liability and Protection for HOA Boards
Running a condo association board in Vail means managing millions in assets while fielding complaints about everything from parking to pipe bursts. General liability coverage protects the association if someone slips on an icy walkway or gets hurt in the pool area. But general liability alone doesn't protect the people making decisions.
Directors and Officers (D&O) Liability Essentials
D&O insurance covers board members personally when they're sued for decisions made in their capacity as directors. This includes allegations of mismanagement, failure to maintain reserves, improper enforcement of covenants, or mishandling construction defect claims.
Colorado's "Dream Act" (HB25-1272), effective January 1, 2026, now requires a 65% majority vote of all owners before an association can file a construction defect lawsuit against a developer. That changes the liability calculus for boards significantly. If your board pursues or declines to pursue a defect claim, D&O coverage protects individual directors from personal financial exposure either way.
Most carriers offer D&O limits for associations. For a high-value Vail property, we'd recommend ensuring limits are sufficient to protect individual directors from personal financial exposure.
Cyber Liability for Luxury Property Management
Associations store sensitive owner data: bank account numbers for auto-pay assessments, Social Security numbers from rental applications, and financial records. A data breach or ransomware attack on your property management company's systems exposes the association to notification costs, legal fees, and regulatory penalties.
Cyber liability policies for HOAs are available to provide coverage for data breaches. Given that many Vail condos use third-party management platforms with varying security standards, this is a gap worth closing.
Mitigating Risks for Short-Term Rental Properties
Vail's rental market means many units cycle through dozens of guests each ski season. Short-term rentals introduce risks that standard condo insurance wasn't designed for: guest injuries, property damage from unfamiliar occupants, and liability from amenities like hot tubs and ski storage rooms.
Your master policy likely excludes or limits coverage for commercial rental activity within individual units. Unit owners renting on platforms like Airbnb or VRBO need a specific short-term rental endorsement or a separate landlord policy on their HO-6. The association should also verify that its general liability policy doesn't contain a short-term rental exclusion for common areas.
One practical step: require proof of rental insurance from any owner listing their unit. This protects the association from being dragged into claims that originate inside a rented unit. Boards that ignore this exposure are setting themselves up for an ugly special assessment after a guest injury.
House Bill 26-1099, effective August 12, 2026, now
requires developers of new condo projects to fund an independent 30-year reserve study before handing control to the HOA. For existing associations, this signals a broader regulatory push toward financial transparency and adequate reserves, both of which directly affect your insurability and premium costs.
Common Questions About Vail Property Insurance
Does my HO-6 policy cover damage from ice dams? Usually, yes, but only for interior damage to your unit. The exterior repair and any damage to common elements falls under the master policy. Check both policies for sublimits on water damage.
Can the association pass the entire master policy deductible to one unit owner? It depends on your governing documents. Many Vail associations have amended their declarations to assign deductible responsibility to the unit where a loss originates. Review your CC&Rs carefully.
What happens if our deductible exceeds Fannie Mae's new $50,000 cap? Buyers seeking conventional financing may be unable to close on units in your building. The board will need to either lower the deductible, which raises premiums, or find creative structuring with your insurance broker.
Is wildfire coverage guaranteed in Vail? No. Several standard-market carriers have restricted or exited wildfire-prone zones in Colorado. Your association may need to place coverage through a surplus lines carrier, which typically costs more but provides broader terms.
Do we need separate coverage for the underground parking garage? Underground structures, including parking garages and mechanical rooms below grade, should be specifically listed in the master policy's building schedule. Water intrusion and structural damage in below-grade spaces is a common coverage gap.
How often should we update our building's replacement cost valuation? Every two years at minimum, and annually if construction costs in Eagle County are rising faster than normal. An outdated valuation is the single fastest way to end up underinsured after a major loss.
Making the Right Choice for Your Mountain Investment
Condo association insurance in Vail requires a fundamentally different approach than insuring properties at lower elevations with lower values. The combination of wildfire exposure, snow load stress, water damage frequency, and sky-high replacement costs means every coverage decision carries outsized consequences.
Colorado's insurance market has seen premiums climb over 100% in five years, and the regulatory environment continues to shift under your feet. Boards need to work with brokers who specialize in mountain resort properties, not generalists who treat your building like a suburban complex.
Get your replacement cost appraisal updated. Review your D&O limits. Verify that short-term rental activity isn't creating a coverage gap. And make sure every unit owner understands what the master policy does and doesn't cover, because the next special assessment could be the one that catches someone off guard. Your mountain property is too valuable to insure on autopilot.
ABOUT THE AUTHOR:
John Jacquat
As President of Pure Risk Advisors, I’m dedicated to helping clients protect what matters most through clear, personalized insurance solutions. Since 2009, my focus has been delivering trusted coverage and guidance for individuals and businesses across Colorado and beyond.
The Pure Risk Process
Process of Working With A Business Insurance Agent in Colorado
Risk Analysis & Tailoring
Embark on a meticulous exploration of your business's unique vulnerabilities and aspirations. Pure Risk Advisors goes beyond mere coverage, ensuring you're equipped with solutions finely tuned to Colorado’s distinct business landscape.
Strategic Business Consultation
Dive deep into a strategic session with our seasoned specialists. By delving into your business model, aspirations, and challenges, we align our insurance recommendations not just to protect but to propel your business forward, keeping in mind Colorado’s intricate regulatory environment.
Swift Policy Integration
Upon discerning the optimal protection strategy, we streamline the activation process. Partnering with Pure Risk Advisors means more than just business insurance – it's about securing your enterprise's future with unmatched diligence and expertise in Colorado.
Pure Risk Advisors Team
Meet Our Colorado Professional Team Members
Meet the heart and soul of Pure Risk Advisors: our exceptional team. Each individual has been meticulously selected not just for their deep-rooted industry knowledge, but for their passion and commitment to genuinely serve our clients.
We pride ourselves on forging more than just business transactions; we build relationships. Our team doesn't see you as just another policy number. Instead, they view every interaction as a partnership, crafting solutions that resonate with your unique needs.
Dive in, get to know us, and discover firsthand why our team makes all the difference.
Client Testimonials
Amazing Feedback About Pure Risk Advisors

In today’s insurance marketplace, innovation and originality are important - but unless they’re accompanied by integrity and personalized service, they do little to accomplish a club owner’s goals. ACE National is proud to recognize John Jacquat and his company, Pure Risk Solutions, as one of our top-ranked premier industry providers. John has consistently mastered achievement in leadership, creating the best product for a client’s needs and following through on his word. I can recommend Mr. Jacquat without reserve if you’re in the market for club insurance.
Angelina Spencer
Executive Director of Ace National
Business Insurance Coverage in Colorado
Commercial Insurance Options
Business Owner's Policy
Coverage for property damage, liability, and business interruption combined.
General Liability Insurance
Protects against business liabilities like bodily injury and property damage.
Workers' Comp. Insurance
Covers employee injury costs, ensuring business and worker protection.
Professional Liability Insurance
Guard against professional mistakes, negligence, or services rendered failures.
Commercial Property Insurance
Broad protection against business-related injuries or property damage claims.
Commercial Auto Insurance
Coverage for business vehicles against damage, injury, or liability.
We've been serving Colorado Business Since 2009
Industries Served
Latest News & Blog
Read Our Latest Articles